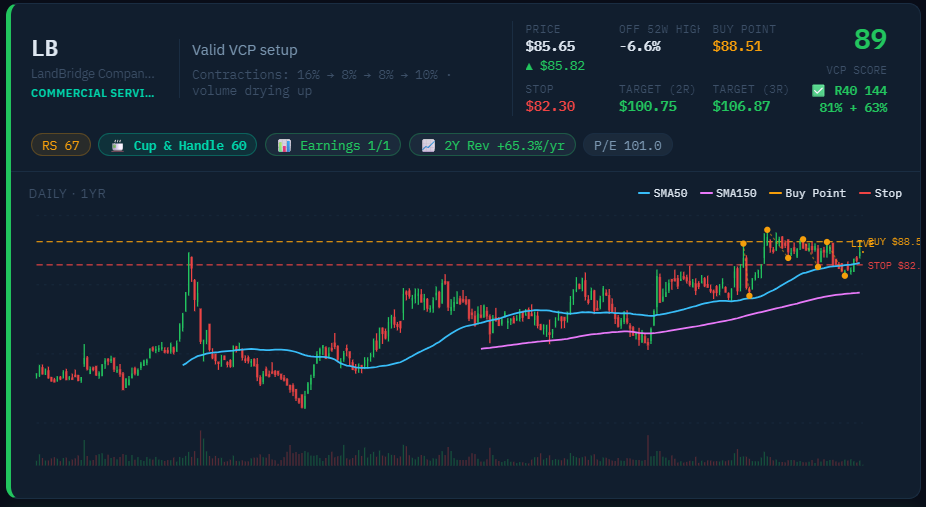
LB isn't simply an oil-and-gas land company anymore.
It owns a huge amount of strategic land in the Permian Basin, and the land can potentially be monetized for:
Oil & gas → water → power → data centers → AI infrastructure
This creates an unusual situation where the existing business already produces substantial cash, while the AI/data-center opportunity is an additional option on top of it.
As of Q2, LandBridge said it was in LOIs, options or late-stage negotiations with seven power/digital infrastructure counterparties representing more than 10 GW of potential power generation across its footprint.
The most impressive thing is the quality of its cash flow.
In 2025, LandBridge generated:
- Revenue: $199.1M, +81%
- Adjusted EBITDA: $177.2M, +83%
- Net income: $72.4M
- Free cash flow: $122M
- FCF margin: 61%
- EBITDA margin: 89%
Those are extremely strong numbers. LandBridge
And Q2 2026 continued the trend:
- Revenue $66.8M, +41% YoY
- Net income $31.0M, +68%
- Adjusted EBITDA $59.8M, +41%
- FCF $40.2M
- EBITDA margin 89%
- FCF margin 60%